A short guide
Understand this dashboard.
The context behind the numbers, in one place.
Budget shares
Share = line amount ÷ the sum of listed amounts in the same budget and income or spending section. Within a selected category, the supporting percentage uses that category’s total. Expand “Budget shares” to see both.
Search never changes the denominator. Each comparison amount uses its own period’s total. Income includes carryover and membership when listed; separate proposed forecasts are excluded. Missing lines have no share. A zero total has no calculable share. Small positive shares display as <0.1%; rounded shares may not add to exactly 100%.
Fundraiser income shares use all activities designated as fundraisers for the selected period, including assumed $0 income. Shares describe allocation, not growth or ROI. Reporting categories reflect the saved classifications.
These are calculated percentages, not published figures. Summed income lines may differ from printed totals; the 2025–26 PDF lists $64,480 of income but prints $58,415, excluding $6,065 of membership and rollover.
Income basis and source differences →01 / Reading the figures
Plans, not actual results.
This dashboard is an independently prepared reference, not an official publication of Summit Drive Elementary School or its PTA. Original budget documents are linked for verification. Report a correction.
- Published
- Amounts transcribed from the supplied budgets.
- Calculated
- Shares, changes, contribution and ROI derived from those amounts.
- Unanswered
- Details not supplied, such as actual collections or remaining cash reserves.
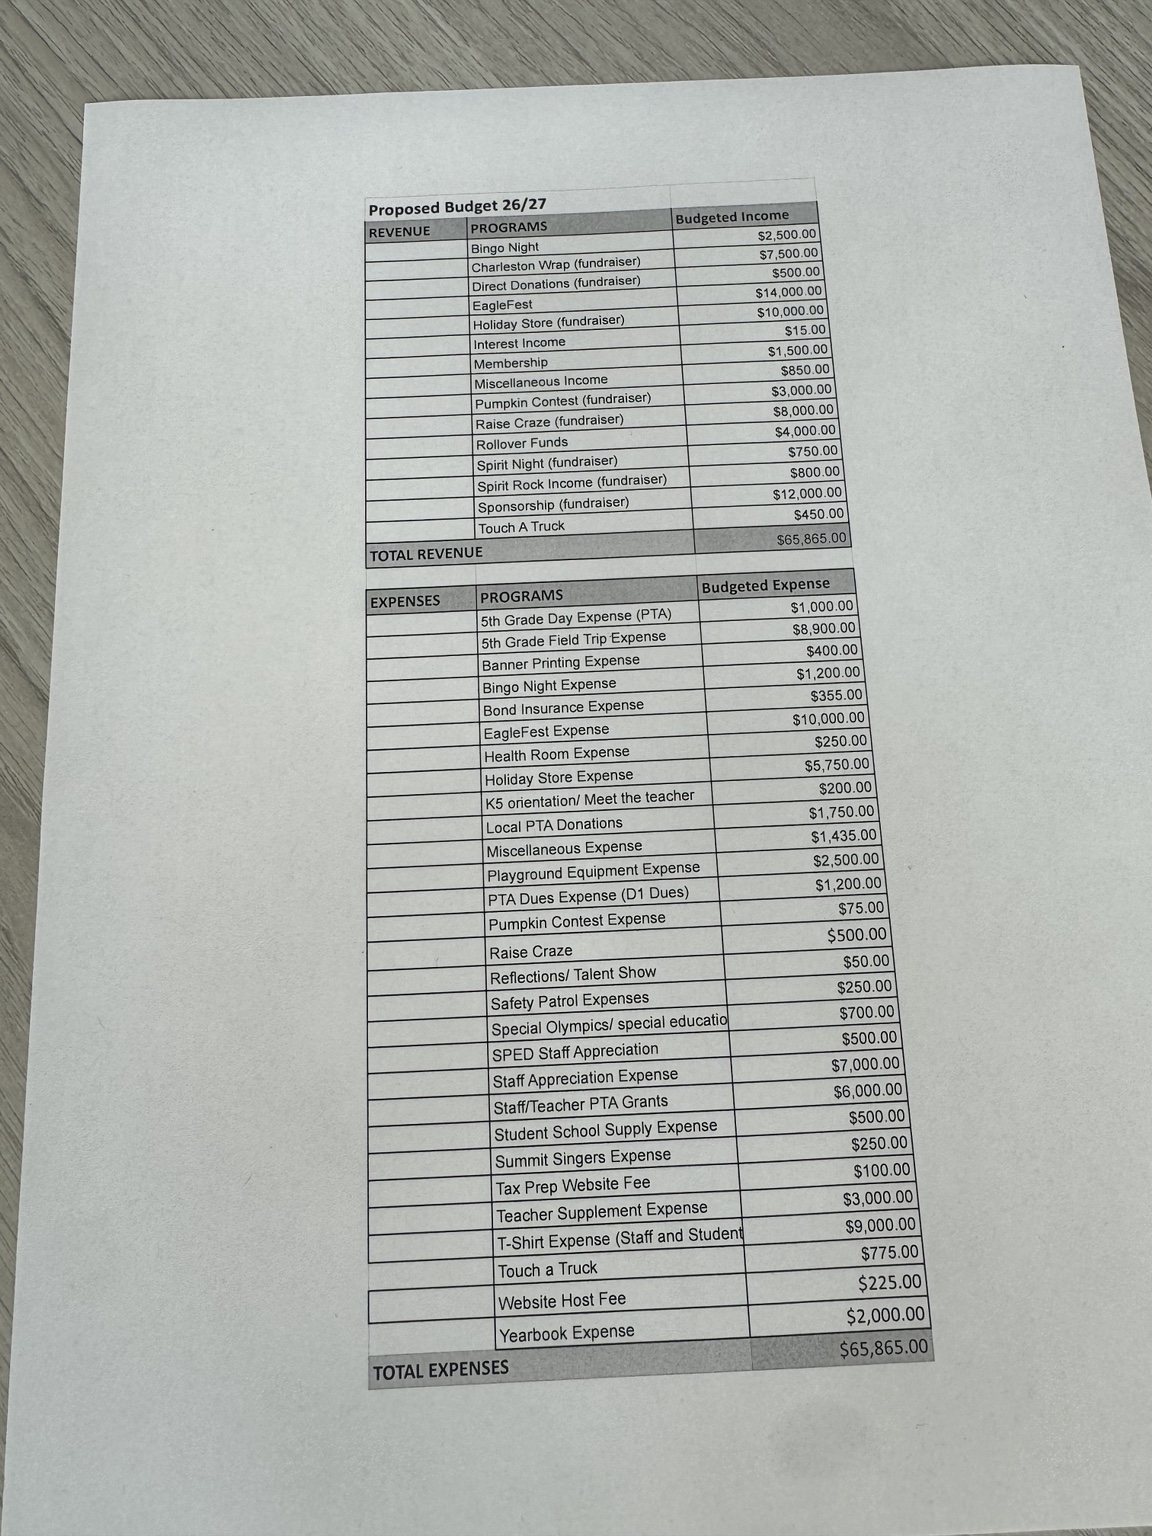
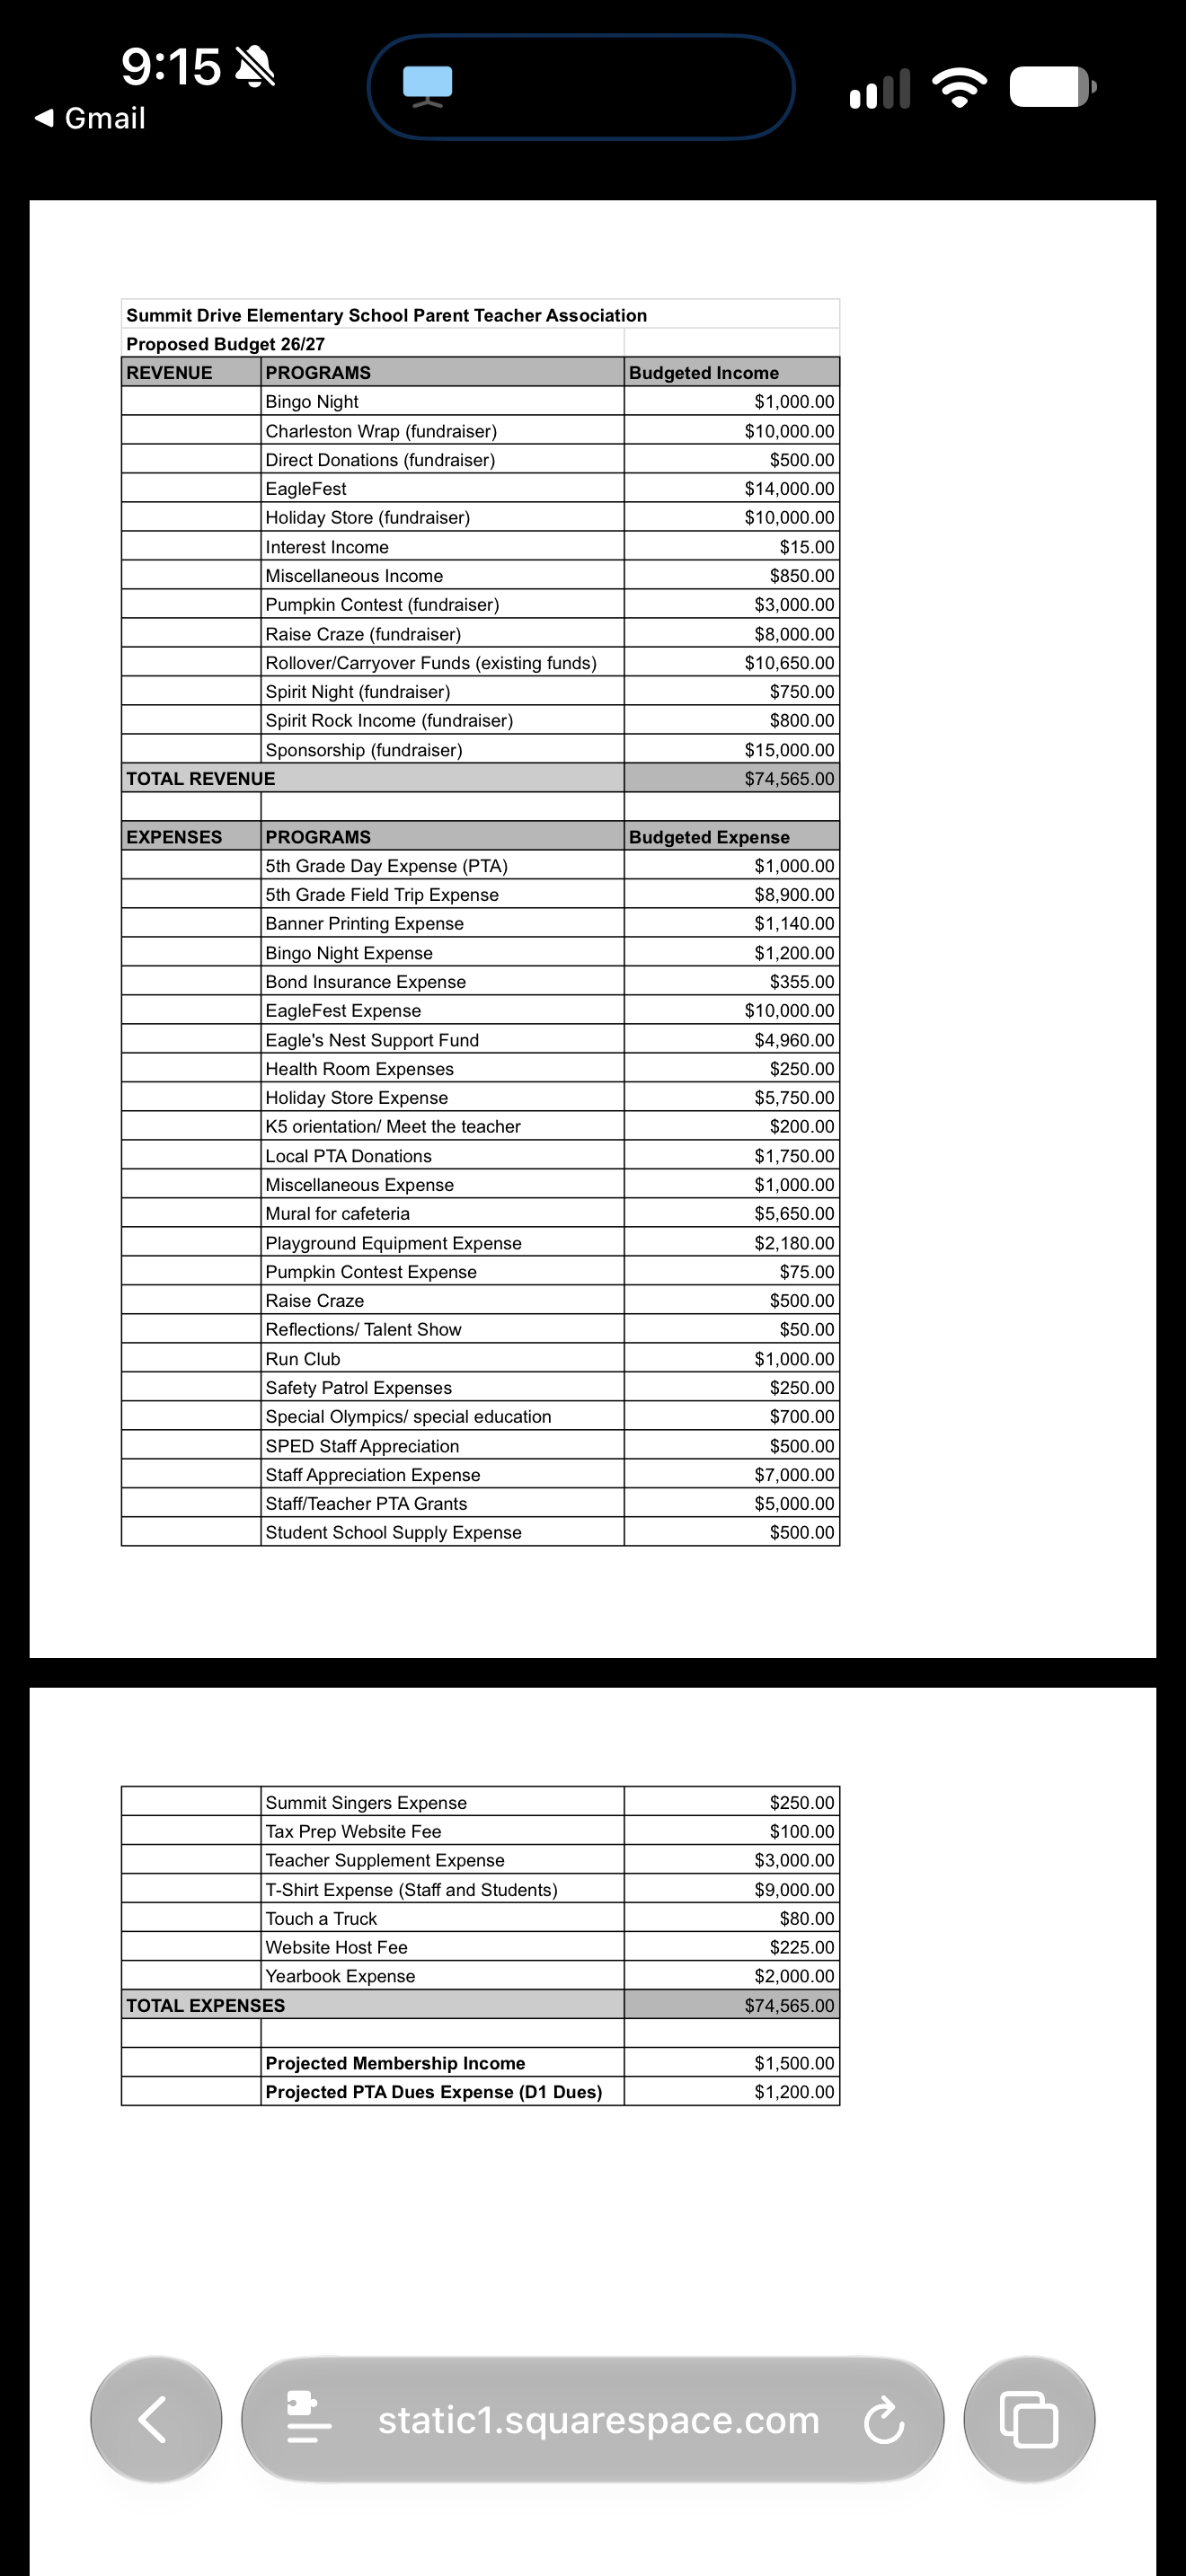
Approved compares the August 2026 baseline for 2026–27 with the supplied 2025–26 PDF. Proposed compares November 2026’s proposal with that August baseline. The August source itself is titled “Proposed Budget 26/27”; it is the owner-designated approved baseline here.
Proposed shows the November figures alongside the approved baseline and changes.
Back to overview →
02 / Fundraiser economics
What “ROI” means here.
ContributionIncome − matched costsROIContribution ÷ matched costs × 100%
Calculations use the dashboard’s saved expense assignments. One expense can belong to one income line; multiple expenses are added together.
- No assigned expense
- Assume $0 expense; contribution equals income.
- Missing income
- Assume $0 income. With a positive expense, contribution is negative and ROI is −100%.
- $0 expense
- Percentage ROI is undefined: “No cost basis.”
- Assigned expense with no amount
- Contribution and ROI show N/A until that amount is known.
These are analytical estimates, not actual profit or full accounting ROI. Unassigned overhead and other undisclosed costs are excluded.
Back to fundraiser performance →
03 / Income
Separate receipts from carryover.
- Carryover is money accumulated earlier, not new fundraising.
- The prior-year PDF’s revenue lines total $64,480, while it prints $58,415. The $6,065 difference equals its $2,000 membership plus $4,065 rollover and is consistent with the PDF’s exclusion note. Both figures are preserved. The proposed $1,500 membership forecast remains below its $74,565 operating total.
- Fundraiser reporting defaults to source lines marked “(fundraiser)”; the dashboard’s saved reporting classifications determine the current selection.
Back to income explorer →
04 / Spending
Categories help you explore.
- Reporting categories are analytical labels, not official accounting classifications.
- Prior-year expenses total $64,080, including $1,000 D1 dues. Approved August 2026 expenses total $65,865, including $1,200 dues. The proposed $1,200 D1 dues forecast is listed below its $74,565 operating expense total.
- Changing a category or expense assignment never changes a published amount.
Back to spending explorer →
Source checks
Do the expense lines add up?
This check compares each published expense total with its transcribed operating expense lines. It does not verify income, actual spending, or the entire budget.
Income totals and exclusions ↗
05 / November amendment
Why the budget expanded.
The November 16 email summary describes using more accumulated funds for school needs after board discussion with Mrs. Woody and input from the South Carolina PTA Treasurer. It identifies partial cafeteria mural funding and possible playground improvements.
- Voting window
- 15 days, as described in that email.
- Announced meeting
- January 14, 2027 · 6 PM · SDE Library.
Back to amendment analysis →
06 / Unanswered
Questions the sources leave open.
- What will the $4,960 Eagle’s Nest Support allocation fund?
- What unrestricted reserve remains after planned carryover use?
- What mural and playground work is planned, and how were priorities chosen?
- How much of the revised revenue targets has actually been collected?
- Why did staff/teacher grants decrease by $1,000?
- Can all members review the financial context before voting?
Back to amendment analysis →
07 / Sources & checks
Trace the figures to the originals.
- Approved baseline & prior-year PDF
- The approved August 2026 baseline has $65,865 income and expense totals. The prior-year 2025–26 PDF prints $58,415 income and $64,080 expense; its listed income totals $64,480.
- November source
- Screenshot supplied November 16, 2026. Operating income and expenses each total $74,565.
- Corrected transcription
- The separate August 2026 amendment baseline lists Playground Equipment at $2,500, correcting the starting HTML’s $500 transcription. The prior-year PDF lists $1,000. The proposed 2026–27 amount is $2,180.
- Email context
- The starting HTML includes a November 16 email summary. The original email attachment was not supplied.
The prior-year PDF, August approved baseline, November proposed screenshot and archived starting HTML remain unchanged. Distinct program labels such as Singing Club and Summit Singers remain separate; no equivalence is assumed. A dash in the full-budget tables means a line was not presented, not that actual cash activity was zero.
This independent explorer is not an official PTA site or audited statement.
View original documents →